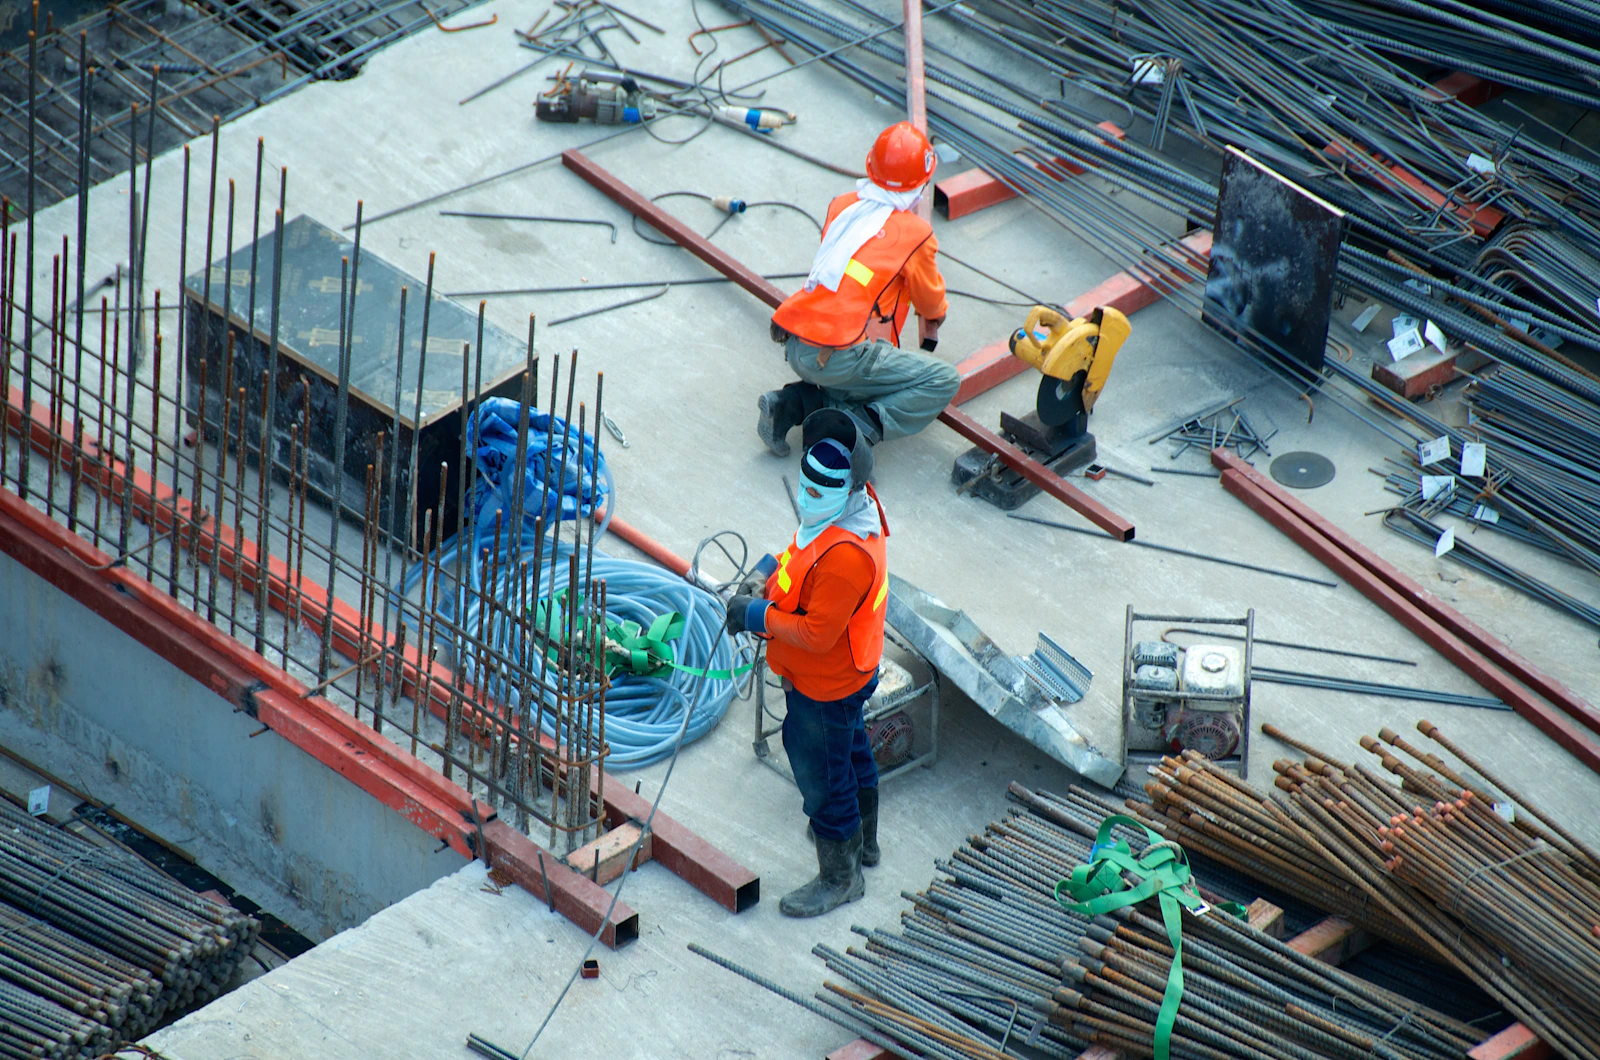
When a construction phase finishes, hired plant can remain on site while everyone moves on to the next task. The machine may be having a quiet week. The hire account may not be.
For construction limited companies turning over more than £1 million across Sheffield, Rotherham, Barnsley and Doncaster, the useful question is not simply whether equipment is being used. It is whether someone has checked its next requirement, made an authorised off-hire decision and followed that decision through to the supplier account.
This is an operational cost-control habit, not a choice between buying and leasing. It connects site decisions with the records your accounts team needs.
Start with what is still on hire
Use a live hire register covering plant, attachments and smaller equipment. Give each item its supplier hire reference, an identifiable asset reference, site, job code, delivery date and responsible supervisor. Where a supplier's reference covers several items, record enough detail to distinguish them.
Add the expected last required date and the next review date. Mark whether an item is working, temporarily idle, awaiting an operational decision or awaiting collection. An idle label is a prompt to ask questions; it is not evidence that billing has ended.
If equipment moves from a Sheffield project to a Rotherham site, record the transfer date and both job references. Check any supplier requirements before moving it. Otherwise, the first job can continue carrying costs after the second job has started using the equipment, making both margins harder to interpret.
Plan the decision before the last working day
Ask the operational lead to confirm whether the equipment is still needed for the remaining work and whether its return can be arranged safely. Review programme changes, dependencies and the practical consequences of bringing equipment back later. Avoid removing necessary equipment merely to make a cost report look tidier.
Once that decision is made, assign someone to handle the supplier communication. Read the actual provider agreement: its terms govern notice requirements, collection arrangements and when charges cease. Do not assume that sending a message, obtaining an off-hire reference or seeing the machine leave the site has the same contractual effect.
Record the notice sent, its date and time, the supplier's acknowledgement, any off-hire reference, the planned collection and the actual collection. Separately record the supplier-confirmed end of charging under the agreement. Keep the supporting correspondence together. If confirmation is unclear, ask the supplier rather than filling the gap with an assumed date.
Keep safety responsibilities separate
A commercial decision to return equipment does not settle the safety arrangements. The HSE's work-equipment guidance explains that duties apply to businesses whose employees use equipment whether they own it or not, and to those who own, operate or control it. Hiring equipment is not a reason to treat safety as somebody else's problem.
The operational lead should confirm what remains necessary and oversee appropriate safe arrangements for return with competent people and the provider. Accounts staff should not direct technical handling or maintenance simply to close an invoice query.
Agree and document who handles maintenance, inspections and defect reporting without assuming that the hire agreement removes statutory duties. HSE's maintenance guidance requires arrangements to keep work equipment safely maintained and says maintenance should be undertaken by competent people. Do not ignore defects or use faulty equipment while waiting for collection.
Reconcile the hire account to the job record
Before approving invoices, match the supplier's item references and billed periods against the register, delivery evidence, transfers and confirmed charging end dates. Check the agreed charging basis rather than applying an imagined standard across suppliers.
A collection record is useful evidence, but it does not by itself prove that every later charge is incorrect. Raise a specific query with the relevant dates and documents. Keep disputed items visible until the supplier explains them or issues an agreed correction.
At month end, reconcile supplier statements with invoices, payments and credits in your ledger. Identify hire charges relating to the period for which invoices have not arrived and discuss appropriate accruals with your accountant. Also flag invoices spanning periods. Do not automatically postpone hire expenses until the customer pays; accounting treatment needs to reflect the applicable policy and circumstances.
GOV.UK's company-record guidance requires records of company spending and debts, plus supporting information needed for accounts and the Company Tax Return. Your hire register is a practical link between that paperwork and what happened on site, not a substitute for it.
Three Actions to Take Next Week
- Review every live hire. Ask each site supervisor to confirm location, job reference, current need and expected last required date. Assign an operational owner to resolve idle items safely.
- Close the communication gaps. Check provider terms and outstanding notices. Capture acknowledgements, collection arrangements and confirmed charging end dates separately, with one named person following up unresolved points.
- Test the records against the account. Reconcile a supplier statement and its invoices to site records, including transfers. Send evidenced queries and give your accountant any outstanding period-end charges to consider.
Make the handover routine
Build this check into the weekly site-to-office handover. The owner needs a short list of unresolved hires, who is deciding and who is chasing, rather than a pile of unexplained invoices.
For help connecting hire records with job-cost reporting and month-end accounts, speak to Tax by Sterling. Which hired item on your sites needs a clear decision before next week's costs accumulate?
Need help with your taxes?
Our team at Tax by Sterling specialises in construction tax. Book a free consultation and let's get your money sorted.
Free Consultation